Pre-Approval & Financing Process
Understanding Your Manufactured Home Financing Options
Why Pre-Approval Matters
Getting pre-approved before you start shopping is one of the smartest moves you can make. Pre-approval gives you a clear picture of what you can comfortably afford, helps you focus on homes within your financing range, and shows our lenders you're a serious buyer. It also helps avoid the disappointment of falling in love with a home that may not fit your budget.
Working With 11 Lenders
As your Manufactured Housing Consultants sales representative, I work with 11 different lenders. This means I can explore multiple financing programs instead of relying on a single lender's limited options. Different lenders have different requirements, rates, and programs. Having access to multiple lenders gives you a better chance of finding a financing option that fits your specific situation.
Financing Options for Every Credit Situation
Whether you have good credit, bad credit, or no established credit history, I can help you explore manufactured home financing options based on your individual circumstances. There is no one-size-fits-all approach. Available programs may include chattel loans, land-in-lieu financing, land and home packages, FHA and VA loans, ITIN financing, down payment assistance, zero-down financing options, and alternative income documentation such as bank statements when available.
Documents You May Need
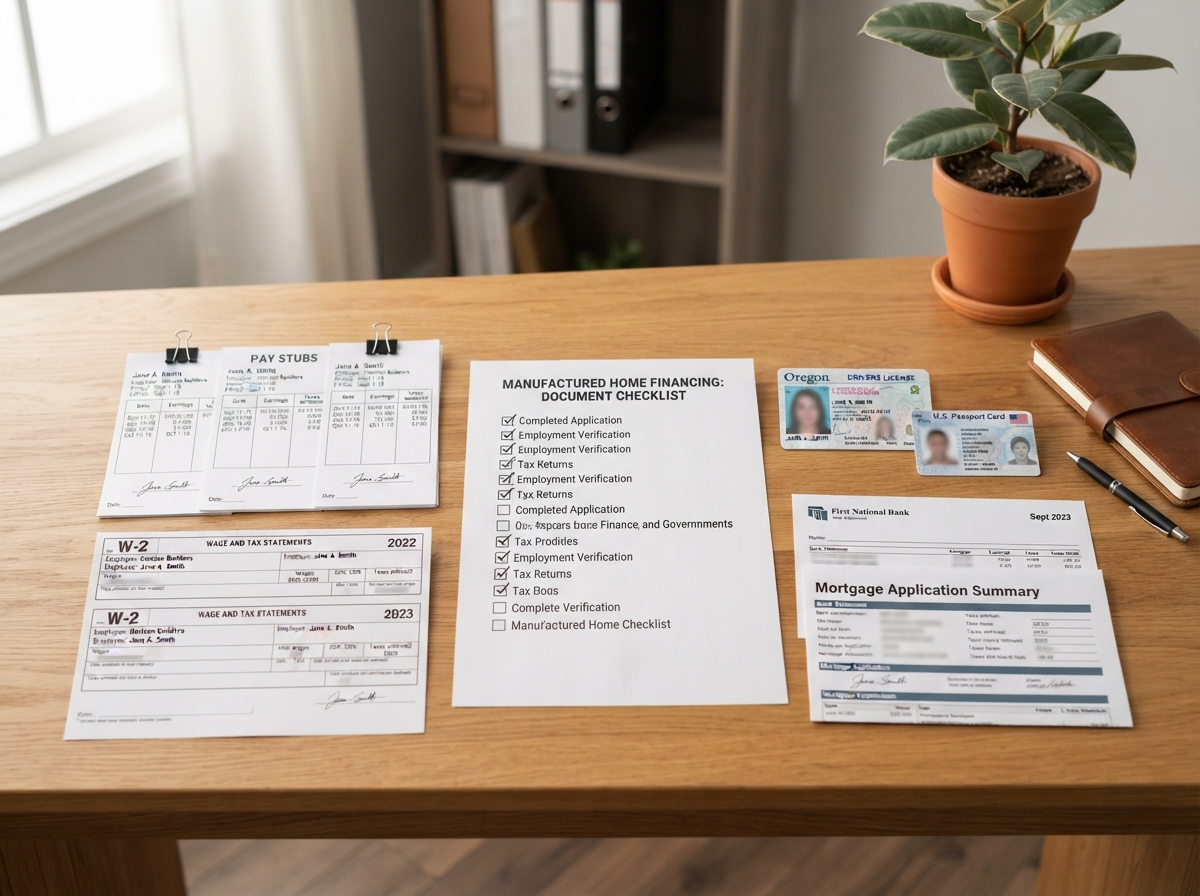
When applying for manufactured home financing, lenders will request the following documents: Your most recent 30 days of pay stubs, 2 years of W-2s or 1099s, your Social Security number, a deed if you already own land, bank statements when required by the lender or loan program, and a valid government-issued identification. Having these documents ready can help make the pre-approval process more efficient. Requirements can vary depending on the lender and loan program.
Income, Employment & Debt-to-Income
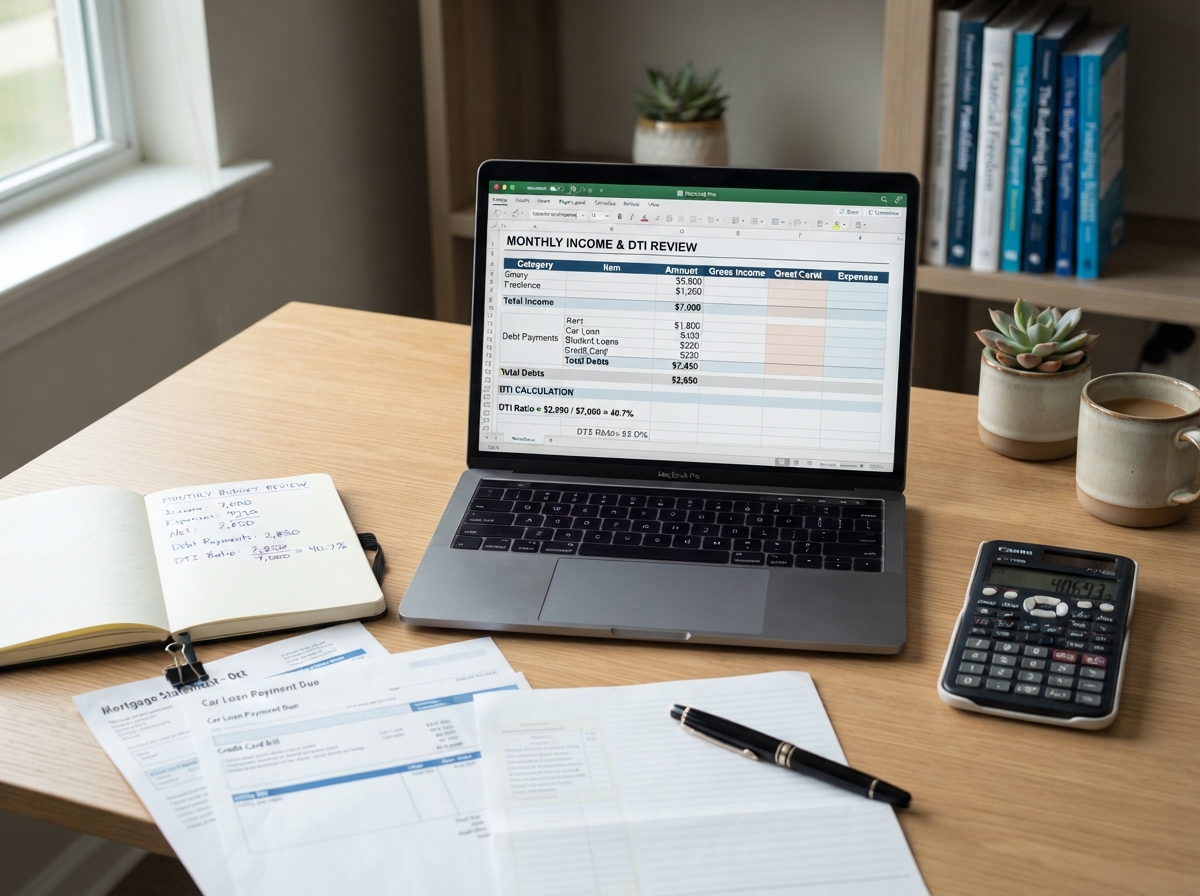
Lenders typically review your income and employment history to help determine your ability to repay the loan. Your debt-to-income ratio, which compares your monthly debt payments to your monthly income, is also an important factor. This may include vehicle payments, monthly credit card debt, mortgages, land payments, qualifying medical debt, and student loan debt. Not every monthly expense is automatically treated as debt. I can help you understand how these factors may affect your financing options.
Down Payment Requirements
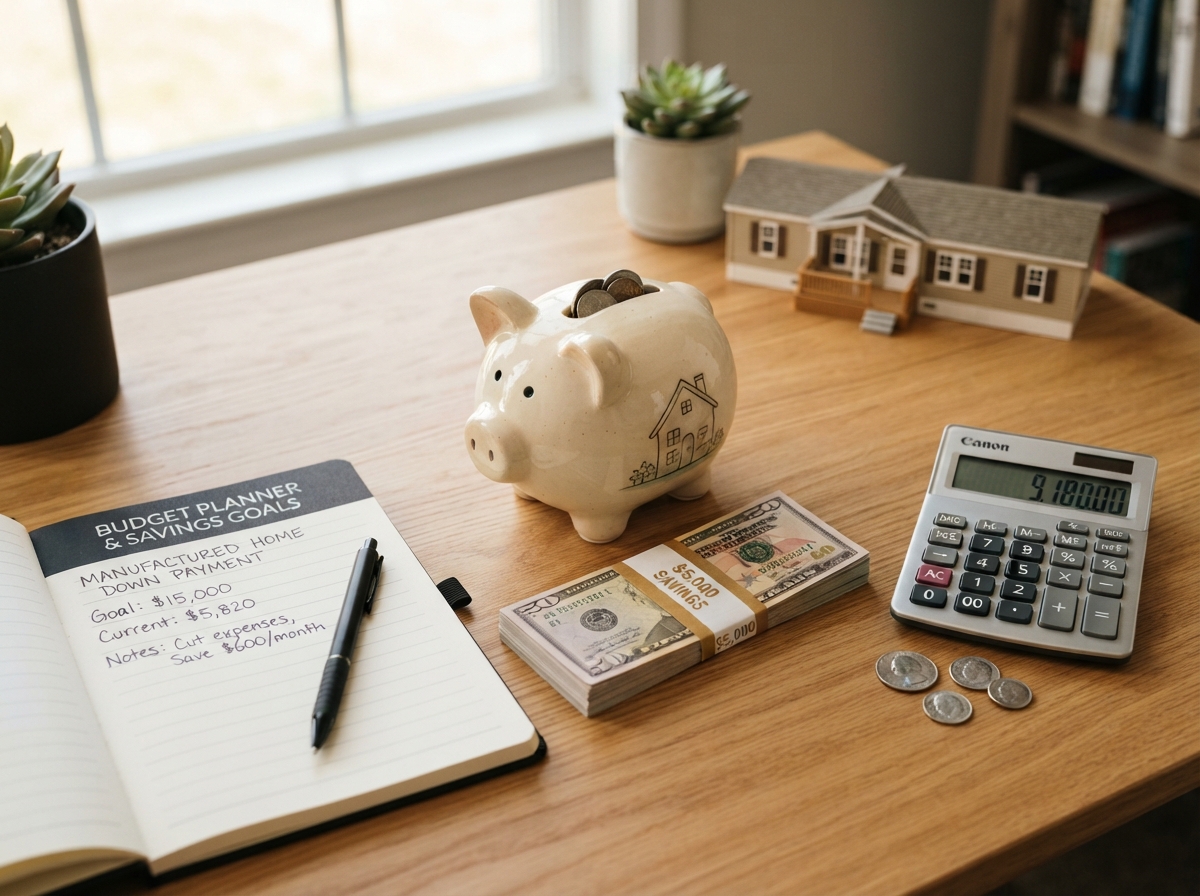
Down payment requirements can vary depending on the manufactured home, loan program, credit profile, and financing structure. A typical down payment is often around 5%, but I also work with lenders that offer 0% down financing without using your land as collateral. I'll be able to help you review the available programs and understand which options may fit your situation.
Financing programs, down payment requirements, rates, and eligibility vary by lender and applicant qualifications. 0% down financing is not guaranteed and is subject to lender approval and program guidelines.
Understanding Loan Program Types
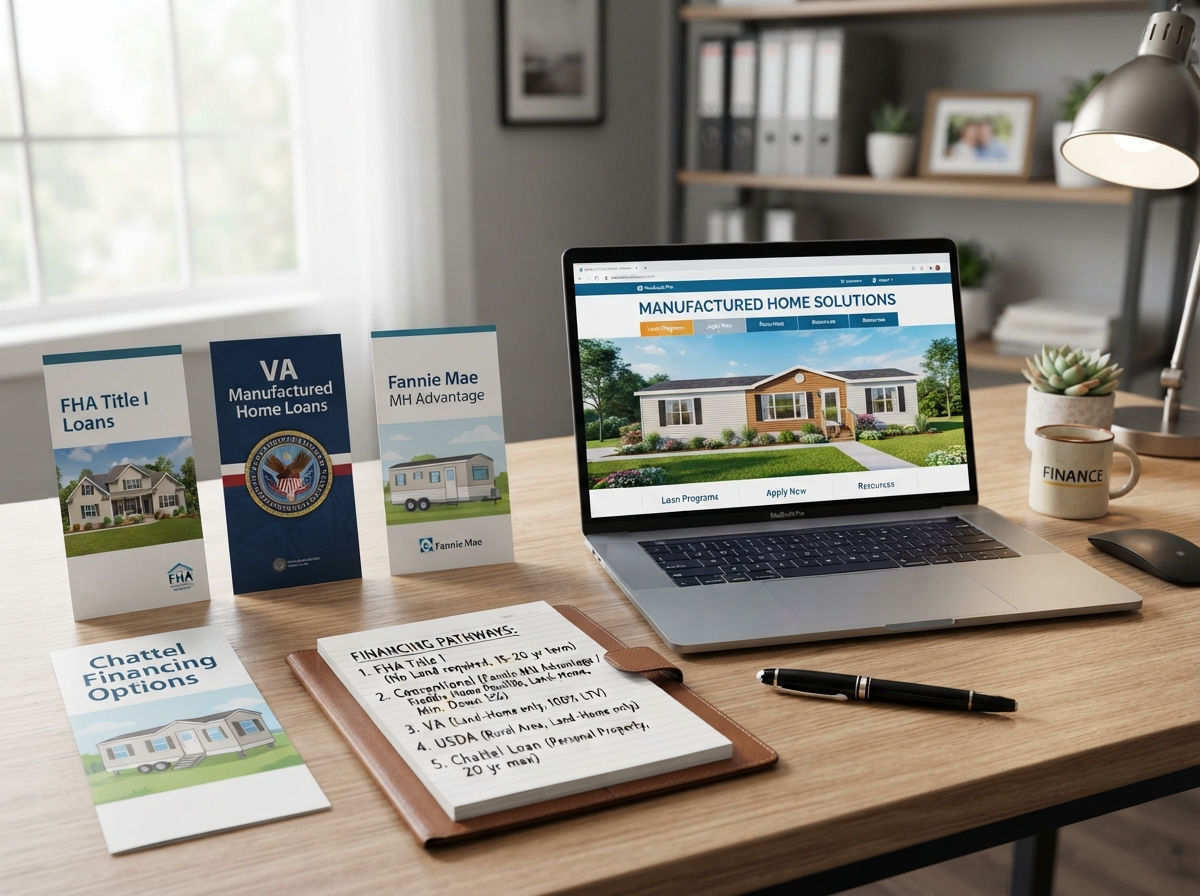
Chattel loans are home only loans used to finance the manufactured home separately from land. If you already own land and it is paid off, land-in-lieu financing may allow the land to be used as collateral toward your manufactured home financing to cover any required down payment (subject to lender guidelines and qualification requirements). Land and home financing combines your manufactured home and land into a single financing package. If you already own land, refinancing may allow you to combine the land with your manufactured home loan and convert the financing into a land and home package. This will provide a more favorable financing terms or a potentially better interest rate. FHA and VA loans are government-backed programs that may offer competitive terms for qualifying buyers. We offer a true 0% down for any client with a 681+ score that also owns land. ITIN financing is available for buyers who use an Individual Taxpayer Identification Number instead of a Social Security Number. Alternative income documentation, such as bank statements, are available for self-employed buyers or those with non-traditional income sources when the lender allows it.
Financing Disclaimer:
Loan programs, interest rates, down-payment requirements, terms, and eligibility vary by lender and individual borrower qualifications. Not every financing option is available to every buyer, and approval is not guaranteed. Final loan approval, rates, and terms are determined by the lender.
Reach out to me for more accurate information and financing options tailored to your specific situation.
What Happens After You Apply
After your financing application is submitted, the lender will review your information, verify the required documentation, and evaluate the application based on its underwriting guidelines. The initial review process typically takes 1–3 business days, but timing can vary depending on the lender, loan program, documentation required, and complexity of your application. I stay involved throughout the process to help answer your questions, coordinate with the lender, and keep things moving forward. Final eligibility and approval are always determined by the lender, not by me.
Ready to Explore Your Financing Options?
Contact me with your questions or take the first step toward getting pre-approved to begin exploring your manufactured home and financing options.